Reinstatement Cost Assessments (RCA) for buildings insurance
A Fire Insurance Valuation, more accurately described as a Reinstatement Cost Assessment (RCA) or Building Insurance Valuation, is prepared to help you set an appropriate sum insured for buildings insurance. It estimates the cost of rebuilding or reinstating the property following a major insured event such as fire, explosion, flood, storm damage or structural collapse.
An RCA is not the same as market value. The declared value for insurance purposes has no direct relationship to the market value of the property, and the assessment is prepared specifically for insurance purposes.
What the assessment typically includes
A Walker Wood Reinstatement Cost Assessment can include allowances for:
- Demolition and debris removal, temporary shoring and associated preliminaries
- Professional fees likely to be incurred in reinstatement
- Reinstatement to a standard equal to the existing building while complying with current legislation and statutory requirements
- Where relevant, external works such as paving and services assumed to be affected by the loss event
- Adjustments for abnormal factors that can materially change cost, for example asbestos, restricted access, attached or mid-terrace locations, listed status, and other site constraints
The Walker Wood approach
We usually start with a site inspection and a review of available drawings and specifications. RICS guidance expects RCAs to be based on a site visit, and notes that desktop-only assessments fall outside the scope of the standard and may not be accepted by insurers.
We then agree with you the full extent of what is to be insured, including clarifying boundaries, external areas and the treatment of fixtures and fittings where lease responsibilities apply.
Cost data and methodology
In most instances, the assessment is calculated using current cost data, commonly referencing RICS BCIS rebuild and reinstatement cost information, with adjustments for the building's specification, complexity and constraints.
For non-standard, complex, historic or Listed buildings, BCIS rates alone may not be appropriate. RICS highlights that a competent surveyor should consider building-specific factors and not rely on standard rates in isolation. In those instances, we can assess reconstruction costs using measured information and an appropriate costing approach, agreed with you before we begin.
Keeping your sum insured up to date
RICS good practice advises regular review, typically an annual desktop update, with a major review every third year, and a full reassessment following substantial alterations.
Case study
Tyzack House
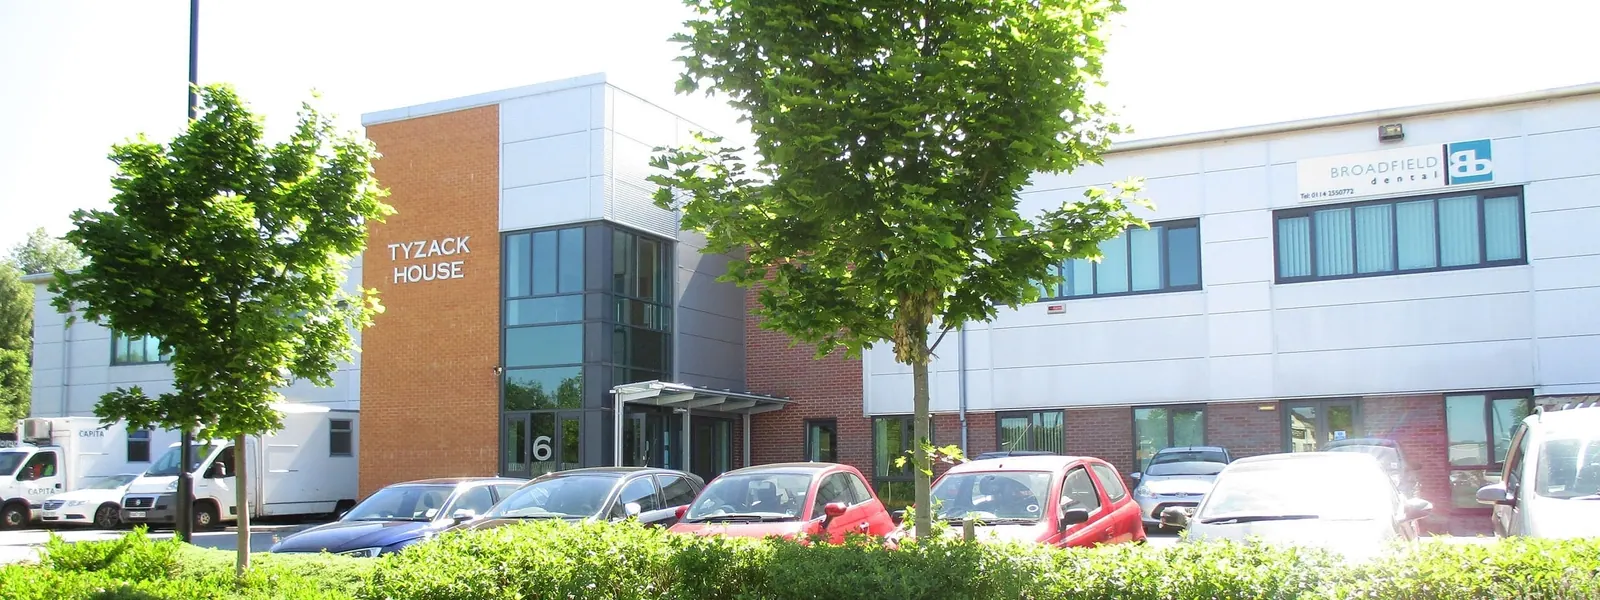
Survey of two-storey offices for investment purposes
Walker Wood completed a Building Survey of a multi-tenanted two-storey office block in Sheffield for a private investor considering its purchase.
Read the case studyFrequently asked questions
What is a fire insurance valuation or reinstatement cost assessment (RCA)?
It is an assessment of the cost to rebuild or reinstate a building after a major insured loss event, used to help set the buildings insurance sum insured.
Is an RCA the same as market value?
No. The declared value for insurance purposes has no direct relationship to the market value of the property.
What costs are included?
RCAs typically allow for demolition and debris removal, professional fees, and reinstatement to a standard equal to the existing building while complying with current statutory requirements, plus relevant external works and abnormal cost factors where applicable.
How often should we review the figure?
RICS good practice advises regular review, commonly an annual desktop update with a major review every third year, plus reassessment after substantial alterations.